A property and construction planning guide for the Hunter Region, NSW.
By Sydney Contracting Engineers (SCE Corp) · Information checked 2 October 2026
A Cessnock new-build investment is an option to investigate for buyers considering a new home or investment property in the Hunter Region. For investors, the 2027 tax changes add another question to the decision: how does an eligible new build compare with an established property under the revised rules?
The answer should bring together the individual property, documented rental demand, purchase and ownership costs, construction status and independent tax advice. SCE’s approved Cessnock townhouse development provides a specific project to explore. Our Cessnock service-location page explains the local building and project-delivery context.
Why new-build eligibility matters
From 1 July 2027, the reform framework preserves negative gearing for eligible new residential properties. Established properties held before 7:30 pm AEST on 12 May 2026 are generally protected by the grandfathering arrangements. Established properties acquired after that announcement face different loss restrictions from July 2027. Buying an established home before July 2027 does not, by itself, preserve unrestricted negative gearing indefinitely. Government tax explainer.
The Government also provides a choice of the 50% CGT discount or the new arrangements for eligible new builds. Confirm eligibility for the particular buyer and property before relying on either treatment. Budget tax-reform summary.
A DA approval alone does not establish eligibility. Treasury’s August exposure draft examines matters including completed housing, lawful occupation, transferable ownership interests and acquisition conditions. The final applicable rules must be checked for the proposed transaction. Draft new-dwelling requirements.
Explore SCE’s approved Cessnock townhouse project
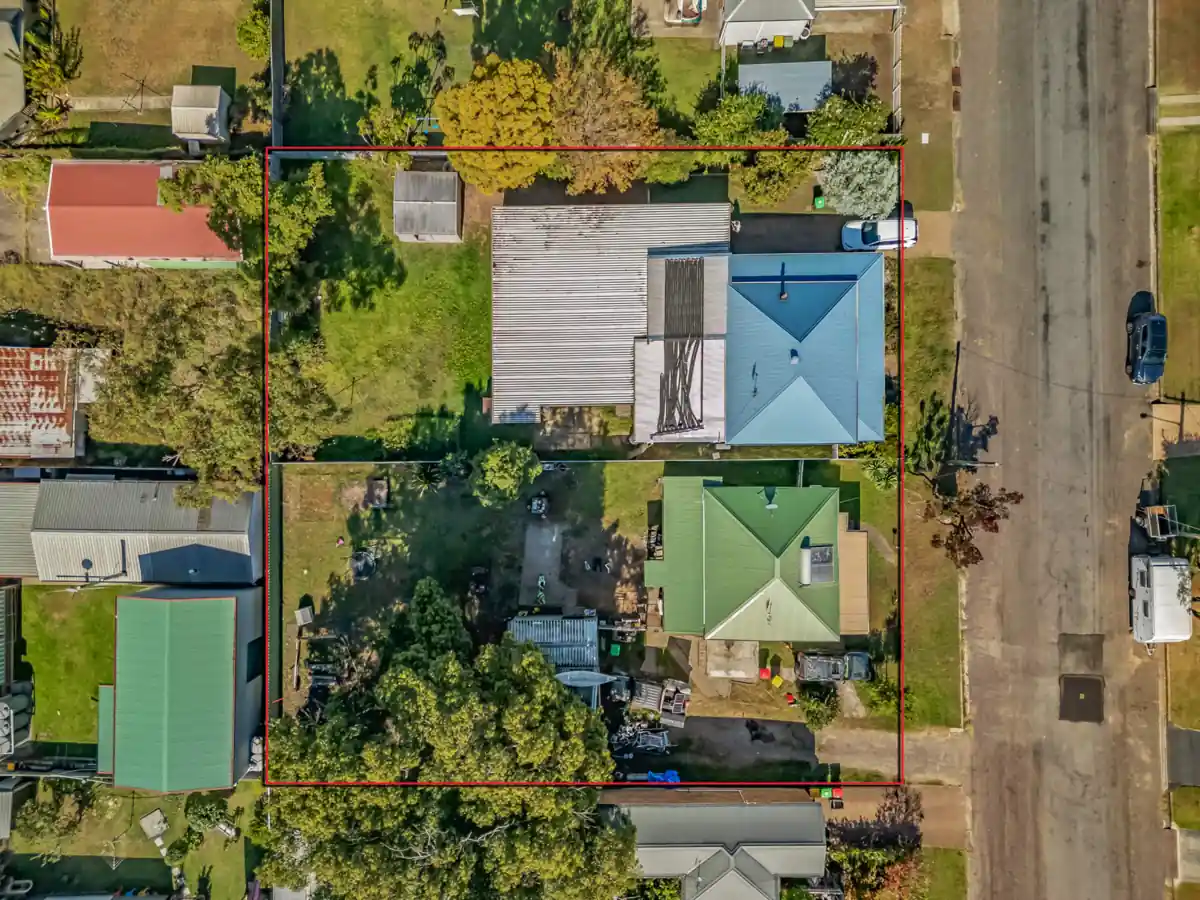
SCE’s published DA-approved development at 18 and 20 Harris Street, Cessnock comprises eight two-storey townhouses: six with two bedrooms and two with three bedrooms.
The project is at pre-construction and consultant-coordination stage. SCE is the developer and intends to deliver the construction as builder and head contractor, subject to the remaining certification and statutory processes.
Interested buyers can enquire about current availability and proposed purchase arrangements. Request the relevant plans, specifications, proposed title structure, price, inclusions, estimated programme and sale documentation for independent review. Project imagery showing the proposed design should be read as concept imagery, not completed construction.
For a proposed new home on another site, SCE’s residential new-build service covers construction delivery. Where feasibility is still uncertain, start with a Core Feasibility and Approval Pathway Review before treating a concept as a buildable commitment.
Assess Cessnock using local evidence
National headlines do not establish the value of an individual Hunter property. Cotality’s September 2026 report said 93% of capital-city suburbs recorded value falls through winter—not 93% of all Australian suburbs. It also recorded a decline in the combined regional index. These figures do not establish Cessnock’s individual performance. Cotality’s market report.
For a specific property, compare recent settled sales of similar dwellings, obtain a current written rental appraisal, and examine competing rental listings and tenant demand. Ask how the layout, parking, maintenance requirements and access to everyday services compare with local alternatives.
Test whether the rental income supports the purchase
A rental appraisal is the starting point for a cash-flow calculation. Allow for vacancy, management fees, rates, insurance, maintenance, applicable land tax and strata costs, as well as the loan repayments. Purchase costs and a financial buffer also matter. Rental income may not cover all outgoings, and a tax deduction does not remove the need to fund the expenses. ASIC Moneysmart’s investment-property guidance.
Have your broker and accountant test the proposed property under less favourable rent, interest-rate and completion assumptions. Keep principal repayments separate from deductible expenses in the calculations.
Plan future equity use without relying on a market bottom
Some buyers consider a regional property as part of a later city-property purchase. Treat that as a scenario to model. Future equity depends on the property’s value and outstanding debt; accessing it also depends on the lender’s valuation, credit assessment and your borrowing capacity.
A workable purchase should not depend on Cessnock prices rising by a particular date or Sydney and Melbourne reaching a predictable low. Include a scenario in which values remain flat and refinancing is unavailable.
Discuss the opportunity with SCE
Tell SCE your preferred dwelling type, intended use, budget range and timing. SCE can explain the development and delivery arrangements; your independent advisers can assess the purchase, funding and tax position.
For broader site questions, see our Hunter Region construction-feasibility guide. To discuss the development, enquire about current Cessnock opportunities.
Frequently asked questions
Does a DA-approved development automatically qualify for the new-build tax treatment?
No. A development approval is a planning milestone. Tax eligibility also depends on the applicable law, the completed dwelling, ownership and acquisition conditions, and the buyer’s circumstances. Obtain transaction-specific tax advice.
Has construction of SCE’s Harris Street townhouses been completed?
No. The published project is at pre-construction and consultant-coordination stage. Ask SCE for the current programme, availability, proposed terms, specifications and sale documentation before making a commitment.
Will rent cover the repayments on a Cessnock investment property?
That must be tested for the particular dwelling and loan. Include vacancy, management fees, rates, insurance, maintenance, applicable strata and land-tax costs, and a financial buffer. A rental appraisal does not guarantee income or positive cash flow.
What should I send SCE when enquiring about the development?
Tell SCE your preferred dwelling type, intended use, budget range and timing. SCE can explain the project and delivery arrangements; your independent legal, lending and tax advisers should assess the proposed purchase.